Friday, September 25, 2026 Never miss a recall or a rule change Get the free brief →
Inside MedSpa
FDA Recall & Compliance Alerts for Medspa Owners
Devices & TechECHOLASER X4 Clears FDA 510(k) for General Surgerylast weekBusiness & M&AAbbVie Files Material Event—Allē Rebate Terms Shifting7 weeks agoDevices & TechVIOL Scarlet Pro Wins FDA 510(k) Clearance2 weeks agoComplianceEvolus Rewards Program Terms Changed—Review Now7 weeks agoDevices & TechHebei Zollvan Diode Laser Clears FDA 510(k)2 weeks agoBusiness & M&ARejuran Maker PharmaResearch Acquires Cosmetic Group5 weeks agoBusiness & M&AAbbVie Files Material Event: Botox/Juvéderm Pricing Shift3 weeks agoBusiness & M&AAbbVie Files Material Event on Allergan Aesthetics5 weeks agoSearch DemandWho Can Inject Botox and Filler in Florida: Scope of Practice and Licensure Requirements4 weeks agoMarketGLP-1 Pill Era Is Forcing Beauty Market Shift5 weeks agoSearch DemandMedical Spa Revenue Calculator: Model Your Practice Economics4 weeks agoSearch DemandGood Faith Exam for Med Spas: State Requirements, Scope, and Compliance4 weeks ago
Starting a Med Spa

The Med Spa Business Plan That Gets Funded: Pro Formas, Assumptions, and Lender Expectations

Lenders don't fund enthusiasm or beautiful renderings. They fund credible assumptions, a realistic ramp, and an owner who clearly understands the unit economics. Here's what a fundable plan actually contains.

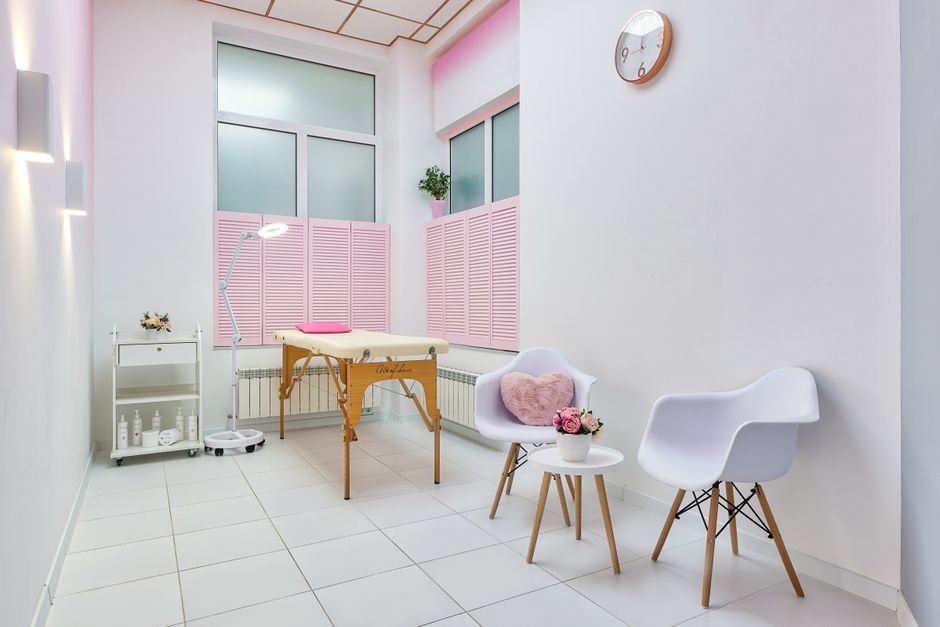
Interior of beauty salon with table for spa procedures and set of skincare products and flower decorations
Photo: Max Vakhtbovych / Pexels

Get the free Inside MedSpa brief by email

The free Inside MedSpa brief · no card · unsubscribe anytime. Privacy.

Walk into a lender's office with a beautiful business plan full of confident revenue projections and rendered interiors, and you'll watch them flip straight past it to the assumptions underneath. Lenders don't fund enthusiasm, and they certainly don't fund renderings. They fund credible assumptions, a realistic ramp, clear unit economics, and — above all — an owner who demonstrably understands their own business well enough to survive being wrong about it. The number they trust least is your revenue projection. What they're really evaluating is whether you understand the levers under that number, because that's what determines whether you make it through the part where the projection turns out to be optimistic.

This is general education for owners, not financial or lending advice.

Free alerts

Free: recall & rule-change alerts for your practice.

Get the recalls and state-law changes that hit your treatment room, in your inbox — free. Unsubscribe in one click.

The free Inside MedSpa brief · no card · unsubscribe anytime. Privacy.

The number a lender trusts least is your revenue projection. The thing they're really evaluating is whether you understand your own assumptions well enough to survive being wrong about them.

They're underwriting your understanding, not your optimism

The instinct of a first-time owner is to make the plan impressive — big revenue, fast growth, a confident path to riches. That instinct works against you, because experienced lenders have seen a hundred optimistic plans and know the top-line number is the least reliable thing in the document. What earns their confidence is evidence that you understand your unit economics and your costs cold — that you know how the business actually makes money, service by service, and what it takes to cover the overhead. A plan that's modest but deeply understood beats a plan that's ambitious but shallow, every time, because the lender is underwriting the owner as much as the venture.

The unit economics a fundable plan shows

The core of a credible plan is the bottom-up build: revenue per treatment and per provider hour, cost of goods by service line, the contribution margin of your core services, and how those stack up to cover fixed overhead. A lender wants to trace the logic from "a treatment earns this much margin" through "a provider can do this many per day" to "that covers the rent and payroll at this utilization." When the plan starts from defensible per-treatment economics and builds up to profitability, it reads as understood. When it starts from a big annual revenue target and works backward, it reads as hoped for — and lenders fund the former.

The ramp is where plans fail

The single most common weakness — the one lenders are specifically hunting for — is an unrealistic ramp. New owners project a full schedule too quickly and under-budget the working capital to survive the slow early months when overhead is full and the book is half-empty. A plan that assumes instant demand and runs out of runway in the gap is exactly the failure pattern lenders have learned to spot. A fundable plan does the opposite: it shows a realistic, slower-than-you'd-hope ramp to break-even and explicitly funds the working capital to survive it. Acknowledging that the early months are slow, and proving you've capitalized for them, is a sign of sophistication, not weakness.

Defensible beats rosy — and beats grim

The right posture for your assumptions is defensible, not optimistic and not artificially conservative. Build assumptions you can justify with logic and comparables, show a realistic ramp, and then stress-test the plan against its own pessimistic case: what happens if demand lags, if the ramp is slower, if a service underperforms? A plan that still survives when you assume things go worse than hoped is dramatically more fundable than one that only works if everything breaks your way. Lenders are risk managers; showing them you've already managed the downside is speaking their language.

What to do

  • Lead with understood unit economics, not an impressive top-line — revenue per provider hour, COGS by line, contribution margin building to cover overhead.
  • Model a realistic, slower ramp and explicitly fund the working capital to survive the early under-utilized months.
  • Make every assumption defensible with logic and comparables, and stress-test the plan against a pessimistic case.
  • Present yourself as the owner who understands the business, because the lender is underwriting your comprehension as much as your concept.

A fundable med spa business plan isn't the most exciting one in the room — it's the most credible one. It shows a lender that you understand how the business makes money, that you've planned for the dangerous ramp instead of wishing it away, and that your plan survives its own bad case. Build that, and you give a lender a reason to trust you with their capital. Build a beautiful projection with shallow assumptions and an instant ramp, and you've made exactly the document experienced lenders have learned to decline.
Frequently asked questions

What do lenders actually look for in a med spa business plan?

Credible, defensible assumptions; a realistic ramp to break-even; clear unit economics; adequate capitalization including working capital for the ramp; and evidence the owner understands the business. They're less impressed by optimistic top-line projections than by a plan that shows you understand your costs and your path to profitability.

What's the most common weakness in these plans?

Unrealistic ramp assumptions — projecting a full schedule too quickly and under-budgeting the working capital to survive the slow early months. A plan that assumes instant demand and runs out of runway is the pattern lenders are specifically watching for.

What are the unit economics a plan must show?

Revenue per treatment and per provider hour, cost of goods by service line, the contribution margin of your core services, and how those build to cover fixed overhead. A lender wants to see that each service makes money and that volume realistically covers the rent and payroll.

How conservative should my projections be?

Defensible rather than either rosy or artificially grim. Build assumptions you can justify, show a realistic (slower than you'd hope) ramp, and stress-test what happens if demand lags. A plan that survives its own pessimistic case earns more trust than one that only works if everything goes right.

Business information, not medical or legal advice. Verify product status at FDA.gov.

Free alerts

Free: recall & rule-change alerts for your practice.

Get the recalls and state-law changes that hit your treatment room, in your inbox — free. Unsubscribe in one click.

The free Inside MedSpa brief · no card · unsubscribe anytime. Privacy.

Share

https://insidemedspa.com/article/medspa-business-plan-that-gets-funded/

Discussion

    Leave a comment

    Comments are reviewed before they appear.
    Inside MedSpa · Free brief

    By the time it's news, it's too late.

    FDA decisions, recalls and the rules you operate under, drafted from the source documents and sent free by email.

    Get the free brief The free Inside MedSpa brief · no card · unsubscribe anytime.
    FDA, recalls and rule changes for practice owners Get the free brief →